Market Letter - Octobre 2026
Currencies: the dollar strengthens, the yen weakens again.
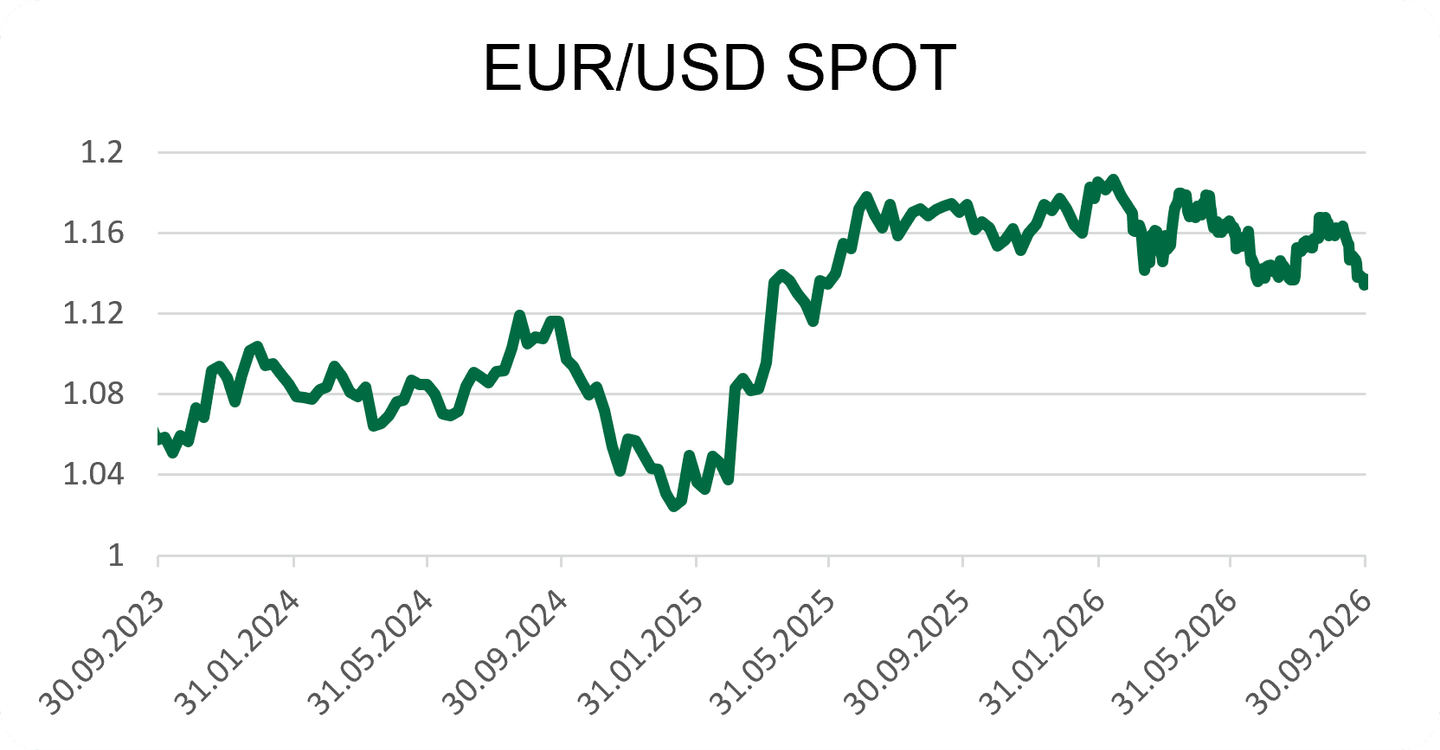
EURUSD: EURUSD is trading around 1.136–1.138, down approximately 2.4% over one month. The euro has therefore given back part of its summer gains. This decline is mainly explained by the interest rate differential in favour of the United States, while Europe’s fragile energy situation and geopolitical uncertainty are increasing the appeal of the dollar as a safe-haven currency.
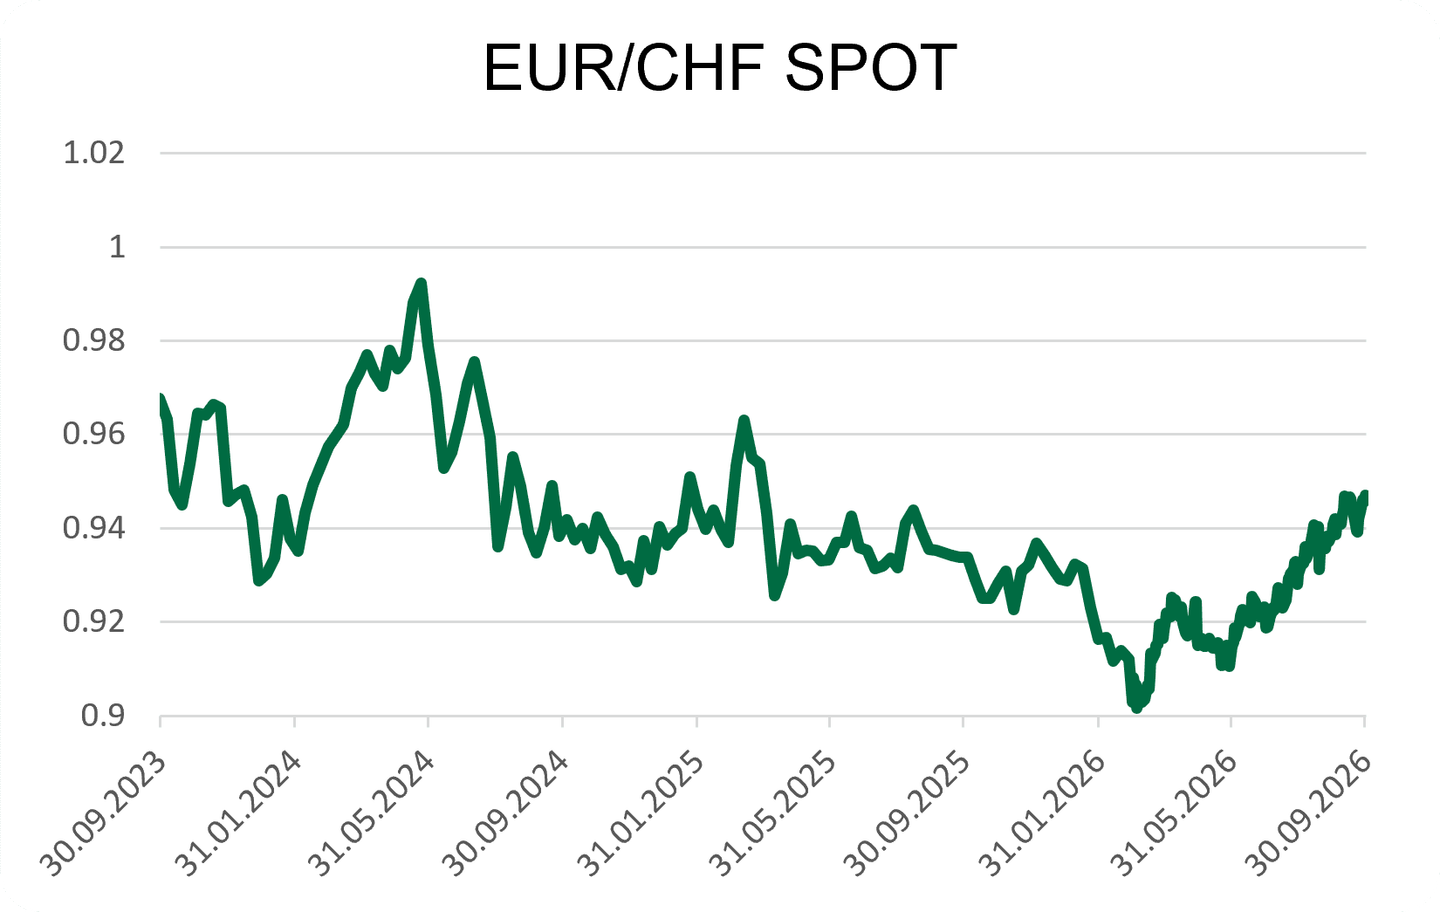
EURCHF: EURCHF is trading around 0.946, up approximately 1.1% over one month.
The euro has therefore strengthened slightly against the Swiss franc. The Swiss National Bank has kept its policy rate at 0%, while Swiss inflation remains relatively moderate at 0.8%. This very low interest rate environment contrasts with the rate increases decided by the Fed and the ECB and reduces the relative attractiveness of the franc.
EURCNY: EURCNY is trading around 7.64, down approximately 2.6% over one month.
The People’s Bank of China has kept its main interest rates unchanged at 3.0% for the one-year rate and 3.5% for the five-year rate.
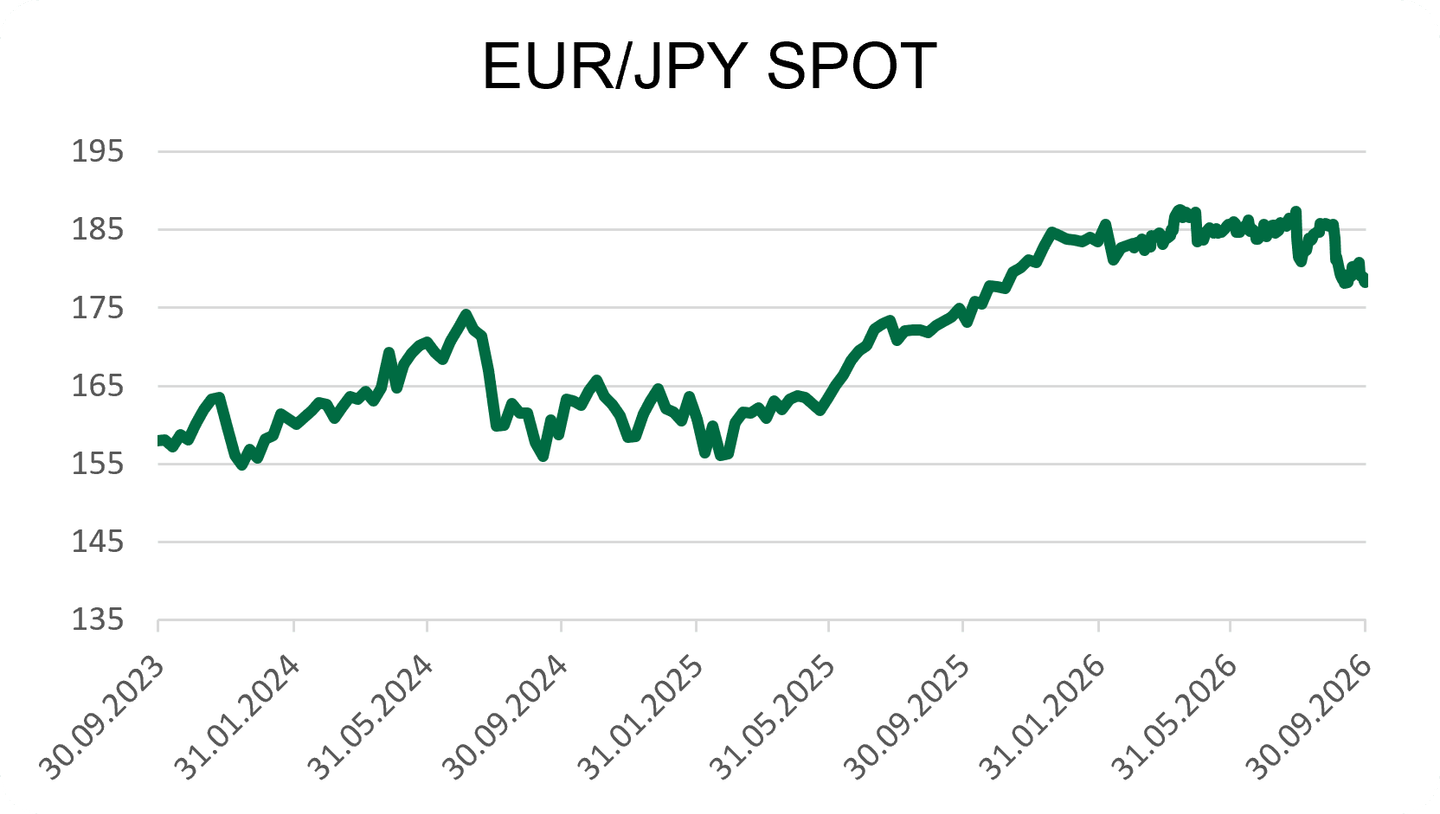
EURJPY: EURJPY is trading around 178.5, sharply lower than the 185 level seen at the beginning of the month. The interest rate differential with the United States remains significant, while US yields rose sharply in September. This yield gap continues to weigh on the Japanese currency and explains its renewed weakness at the end of the month.
EURBRL: EURBRL is trading around 5.94. The Brazilian real remains supported by high interest rates, but the approaching presidential election is creating greater uncertainty. The first round will take place on 4 October 2026, followed by a second round on 25 October 2026.
EURZAR: EURZAR is trading around 18.7. The South African rand remains supported by high interest rates, with the South African Reserve Bank having raised its policy rate to 7.25% in September. However, rising oil prices and geopolitical tensions are weighing on the South African currency and increasing its volatility.
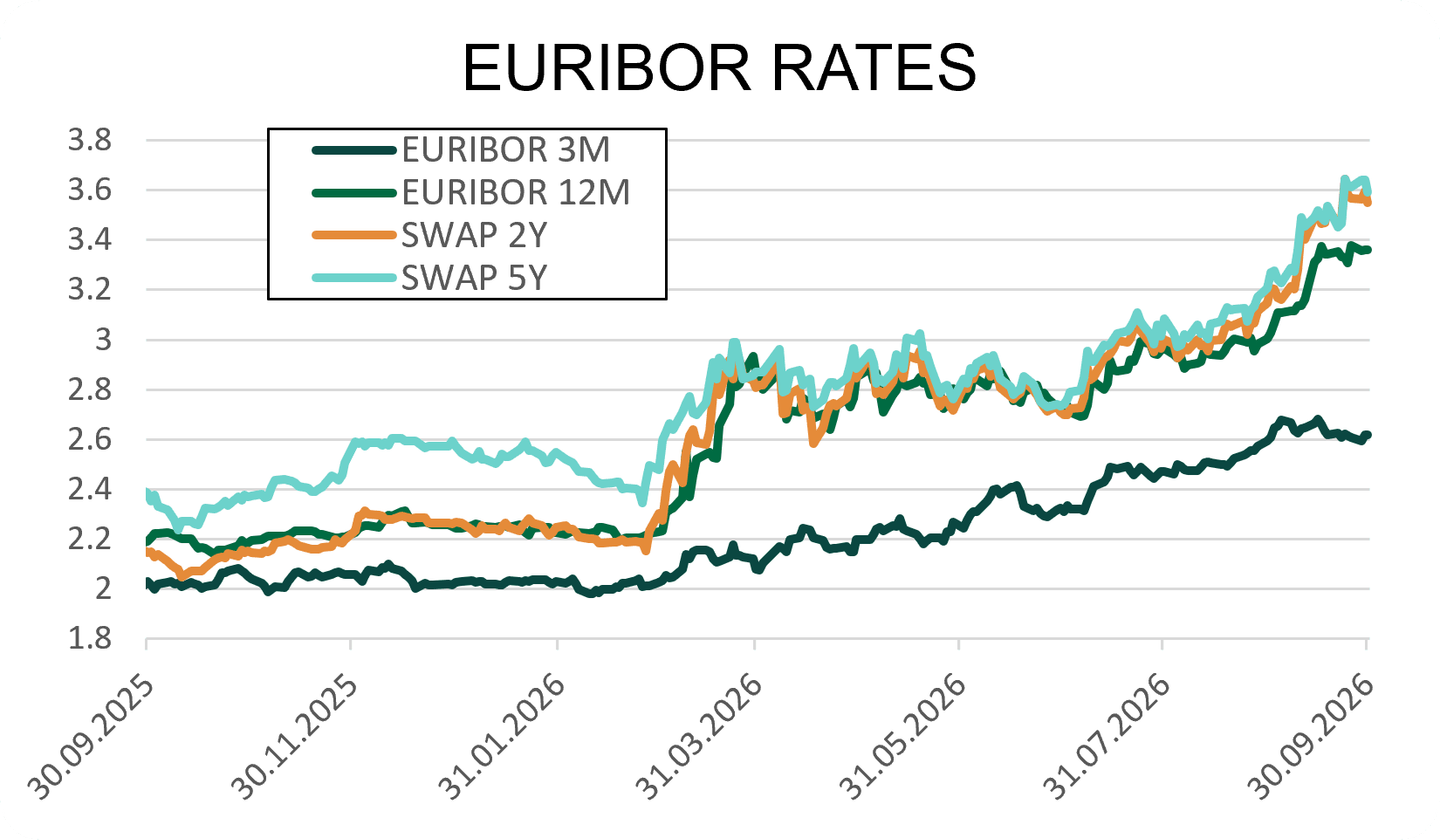
Interest rates: the rise in rates accelerates in the euro area.
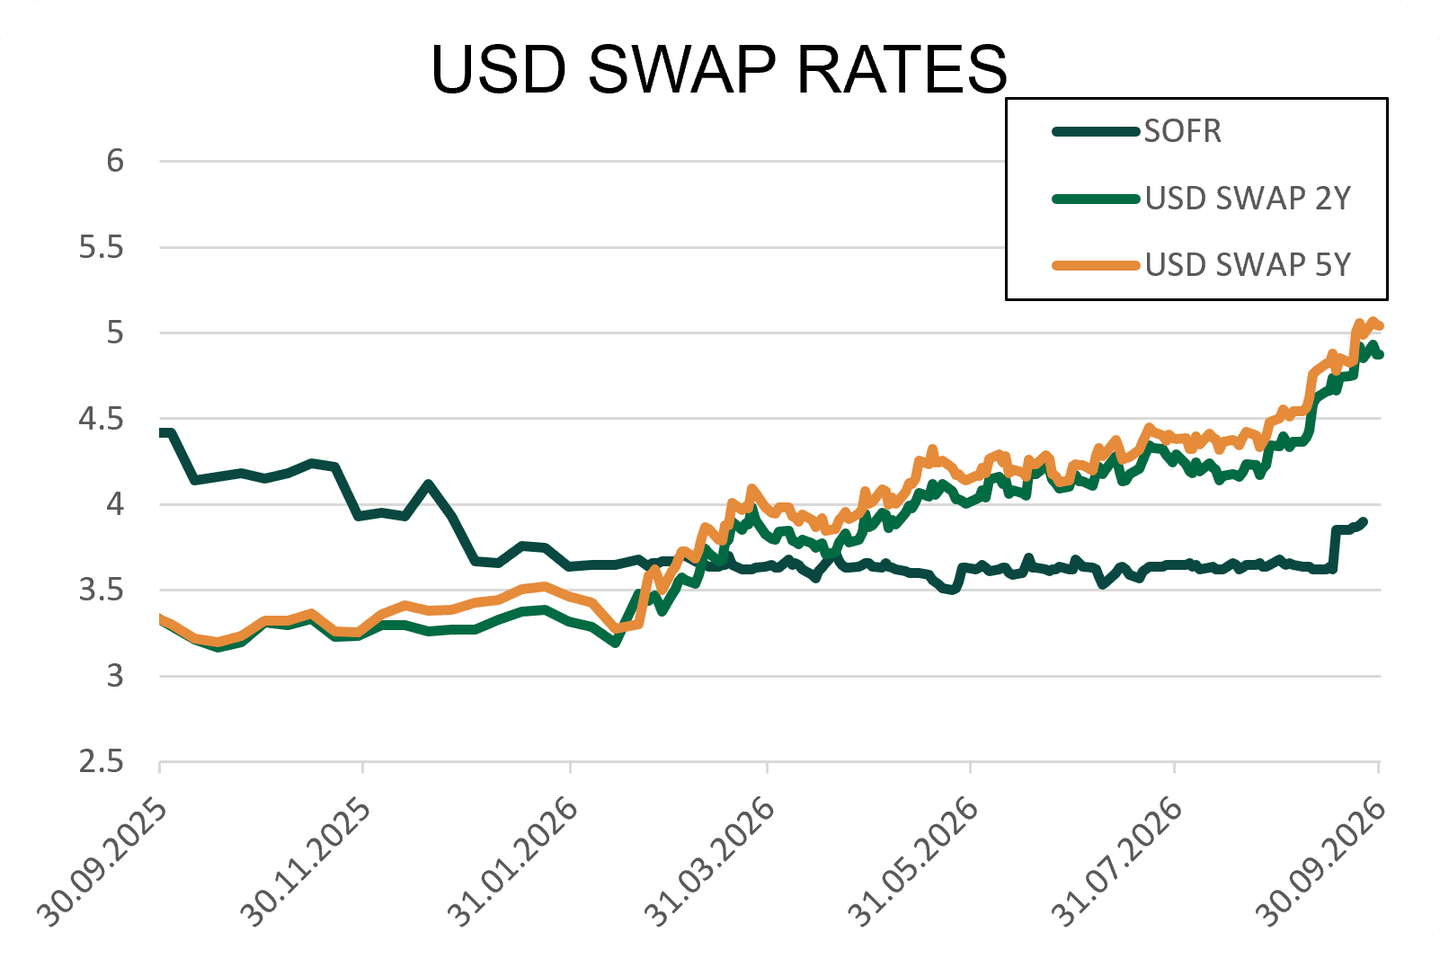
United States: The Federal Reserve raised interest rates by 25 basis points in September, bringing the Fed Funds target range to 3.75%–4.00%. Inflation remains elevated at 3.4% in August, while unemployment is holding at 4.1%, giving the Fed some room to maintain a restrictive policy stance. The decision reflects persistent inflationary pressures, particularly those linked to energy, while the labour market remains strong enough to allow the Fed to continue raising rates. In financial markets, this stance has led to a sharp increase in long-term yields, with the 10-year US Treasury yield trading around 5.2%. As a result, financing conditions for US households and businesses are tightening, particularly in the housing sector and for long-term investment.
Euro area: The European Central Bank also raised interest rates by 25 basis points in September, bringing the deposit rate to 2.50%. Inflation rose to 3.2% in August, from 2.9% in July, while economic activity remains solid: the composite PMI reached 53.1 in September, its highest level in around three and a half years. Rising energy prices are one of the main factors behind the renewed inflationary pressures. At the same time, the resilience of economic activity is allowing the ECB to continue raising rates without, at this stage, triggering a broad-based contraction in the economy.
United Kingdom: The Bank of England kept its policy rate unchanged at 3.75% in September. UK inflation remains elevated at around 3.1%, while economic activity continues to expand, albeit at a moderate pace. For now, the BoE prefers to wait and assess whether higher energy costs will feed through sustainably into wages and services inflation.
Japan: The Bank of Japan raised its policy rate from 1.0% to 1.25% in September, continuing the gradual normalisation of its monetary policy. Inflation remains relatively moderate at around 1.9%, while economic activity continues to expand.
China: The People’s Bank of China kept its main interest rates unchanged in September, at 3.0% for the one-year rate and 3.5% for the five-year rate, for the sixteenth consecutive month. Industrial production remains dynamic, while domestic consumption and the property sector continue to be fragile.
Commodities: sharp rise in commodity prices and increasing supply pressures.
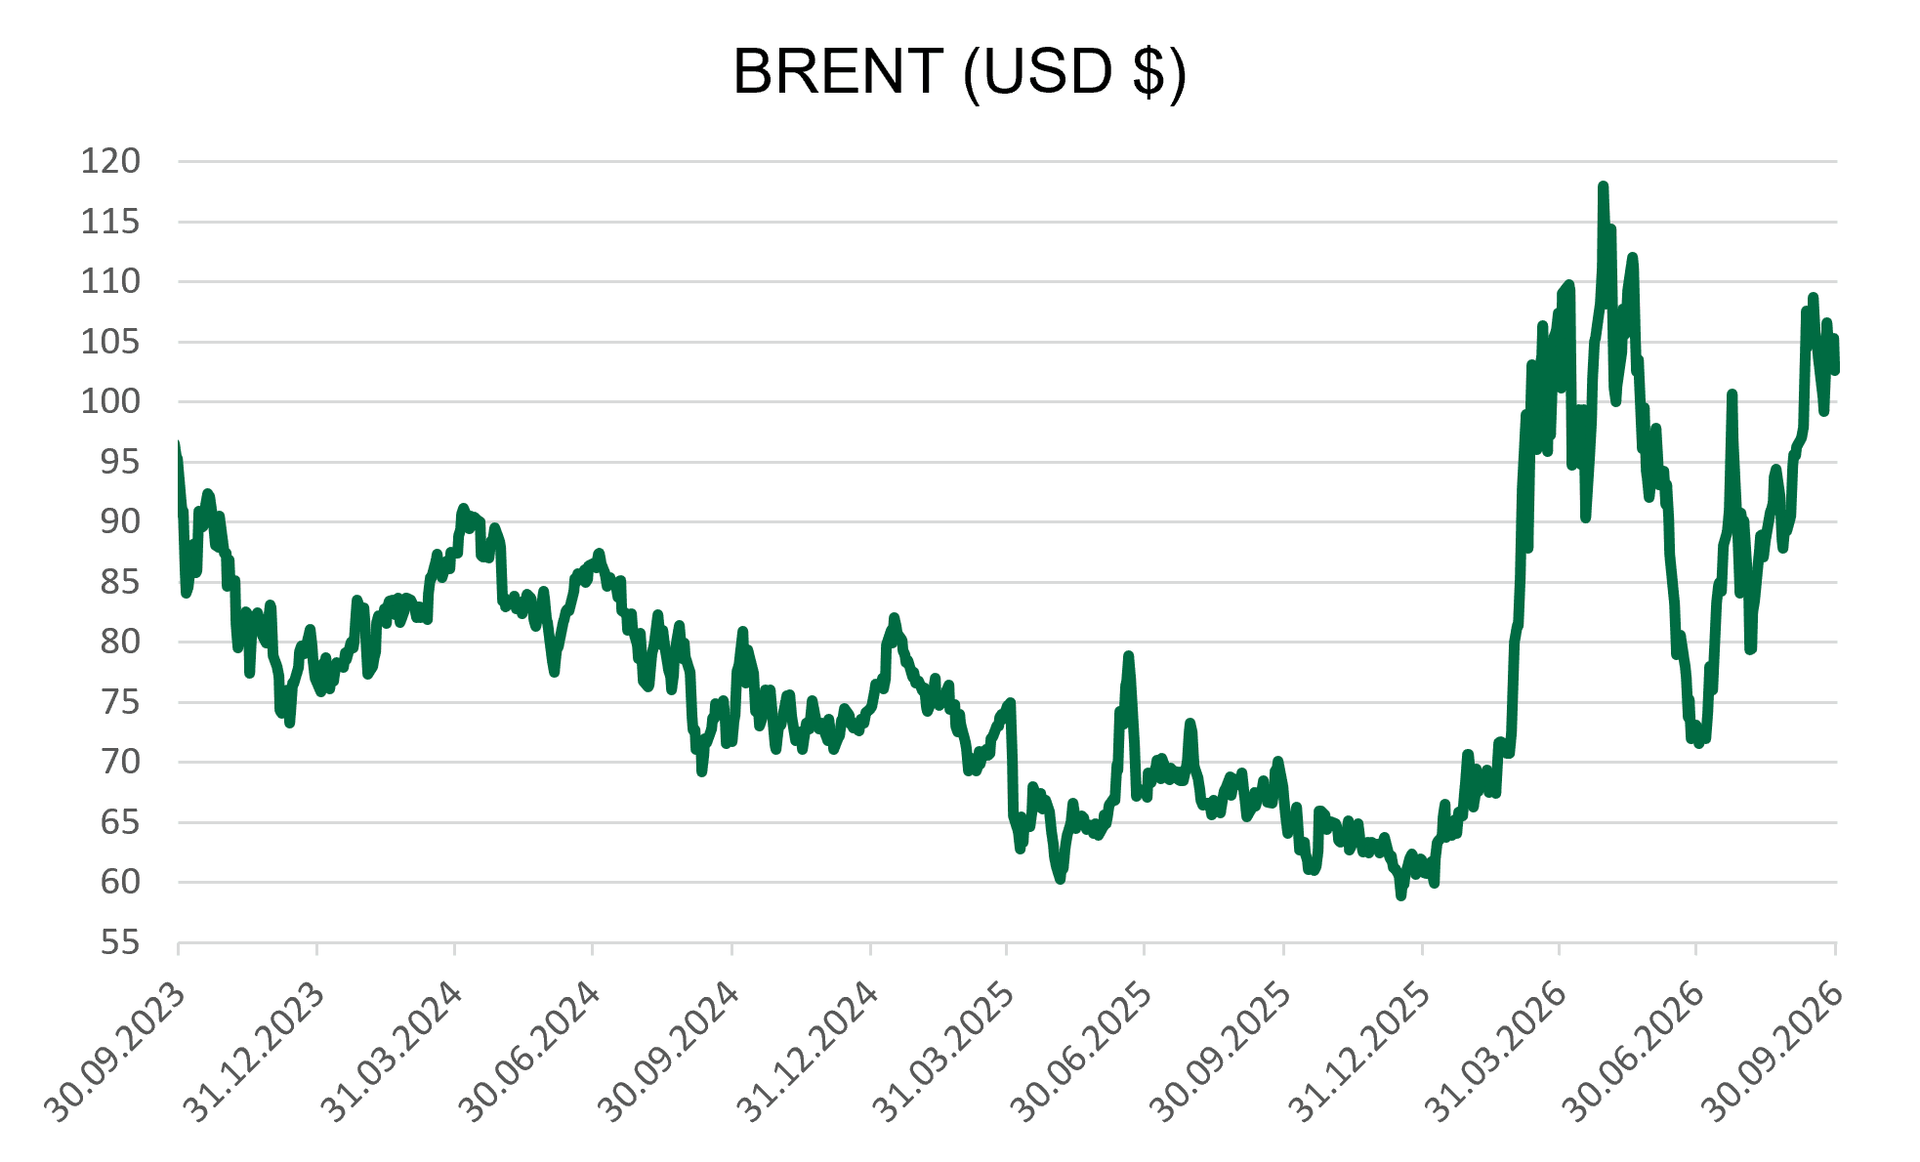
Oil: Brent crude is trading around $107 per barrel, up approximately 18% over one month. The oil market therefore remains under significant pressure after several weeks of gains linked to the conflict in the Middle East. The main driver remains the risk of disruptions to flows from the Gulf, particularly around the Strait of Hormuz. Despite a rebound in regional exports in September, logistical constraints and the use of alternative transport solutions continue to keep a significant risk premium embedded in prices.
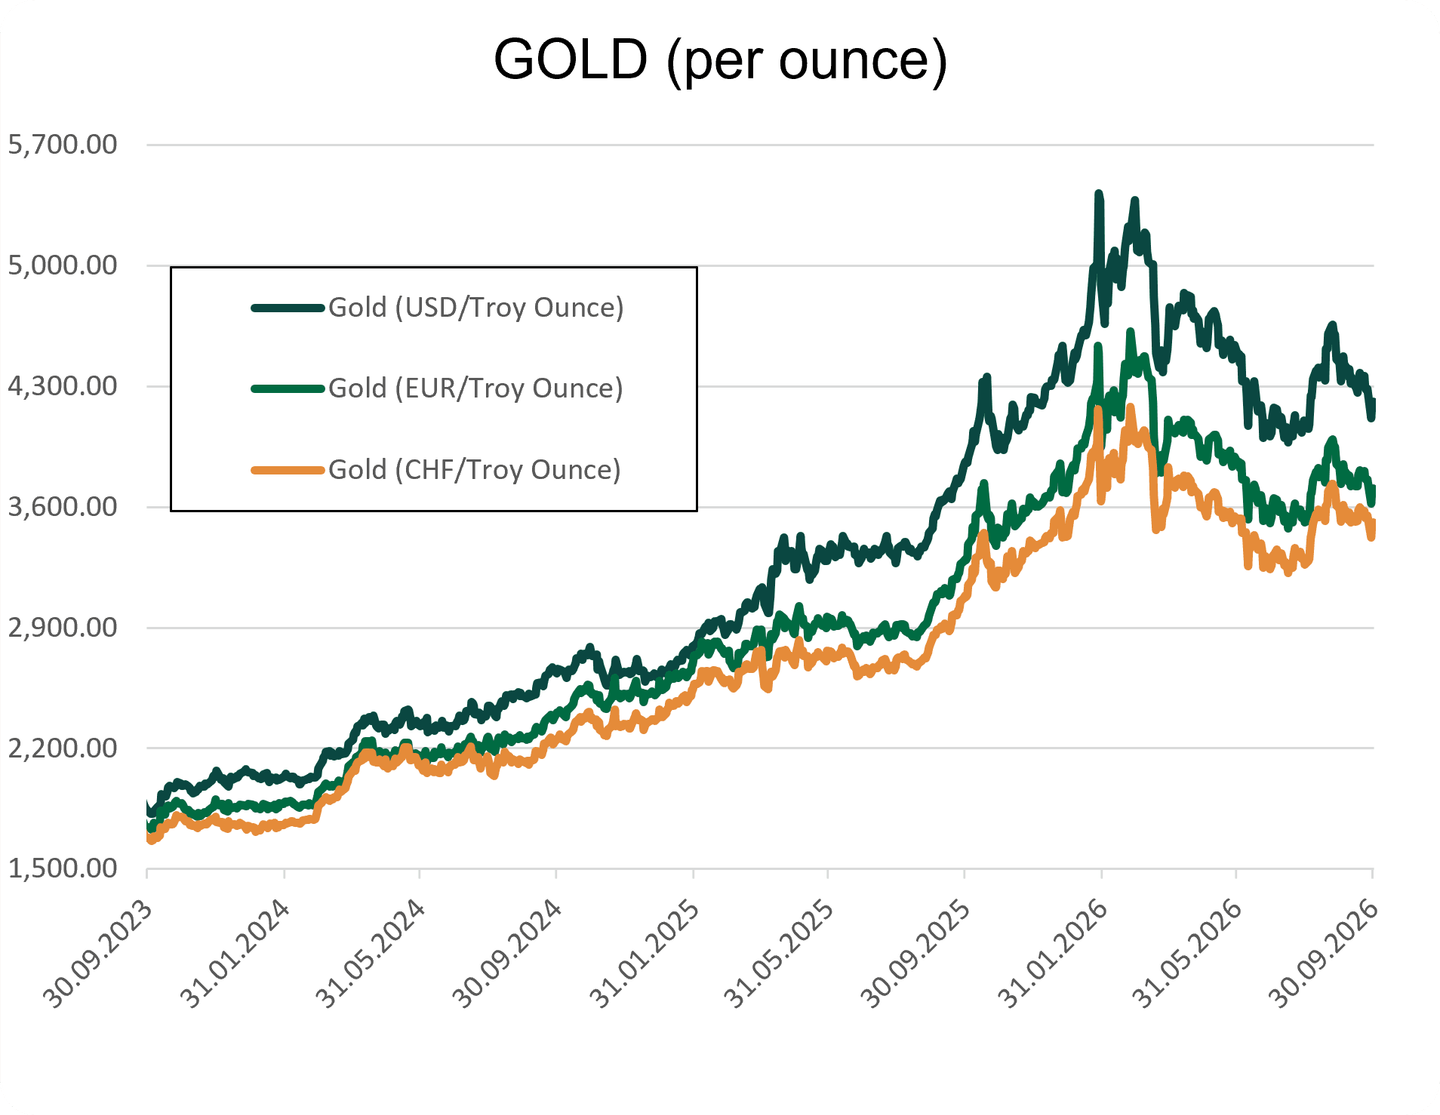
Gold: Gold is trading around $4,130–4,140 per ounce, down approximately 7% over the month and close to a seven-week low. This decline is partly explained by the sharp rise in US bond yields and the stronger dollar. With the 10-year Treasury yield above 5.2%, interest-bearing assets have become relatively more attractive than gold. However, the metal continues to receive support from geopolitical risks and central bank purchases.
Sulfur: Sulfur is trading around CNY 7,735 per tonne. The one-month decline is close to 7%. However, the price remains almost three times higher than a year ago, after reaching a record above CNY 11,000 in June. For producers of sulfuric acid and phosphate fertilisers in particular, cost pressures therefore remain significant despite the pullback from the highs reached in the spring.
Natural gas / LNG: In the United States, natural gas is trading around $3.14 per million BTU, up approximately 7% over one month. The market remains supported by growing demand from LNG export terminals and by occasional production disruptions, although US supply remains abundant.
In Europe, TTF gas is trading around €71–72 per MWh. The monthly increase is now limited to a few percentage points, but prices remain more than twice as high as they were a year ago. More importantly, European storage facilities are only around 70–71% full, compared with a seasonal average of approximately 87%.
The main risk remains LNG supply. The closure of the Strait of Hormuz has sharply reduced Qatari exports, and QatarEnergy has extended several force majeure declarations. The Asian JKM LNG price is now around $26 per million BTU, up approximately 15% over one month.
For European gas-intensive industries, the situation therefore remains fragile as winter approaches. Relatively low storage levels, combined with any further supply disruption or a cold winter, could quickly trigger another sharp increase in prices.
GPU / AI: The cost of high-end computing capacity remains elevated as demand for Blackwell-generation GPUs continues to increase. At Lambda, renting an Nvidia B200 currently costs between $6.69 and $6.99 per GPU per hour, compared with around $4 for an H100. Most industry participants have increased their prices by approximately 20% in recent weeks.
Copper: Copper is trading around $6.56 per pound in the United States, after reaching a record close to $6.85 during the month. On a one-month basis, the price is now broadly unchanged, but it remains approximately 35% higher than a year ago.
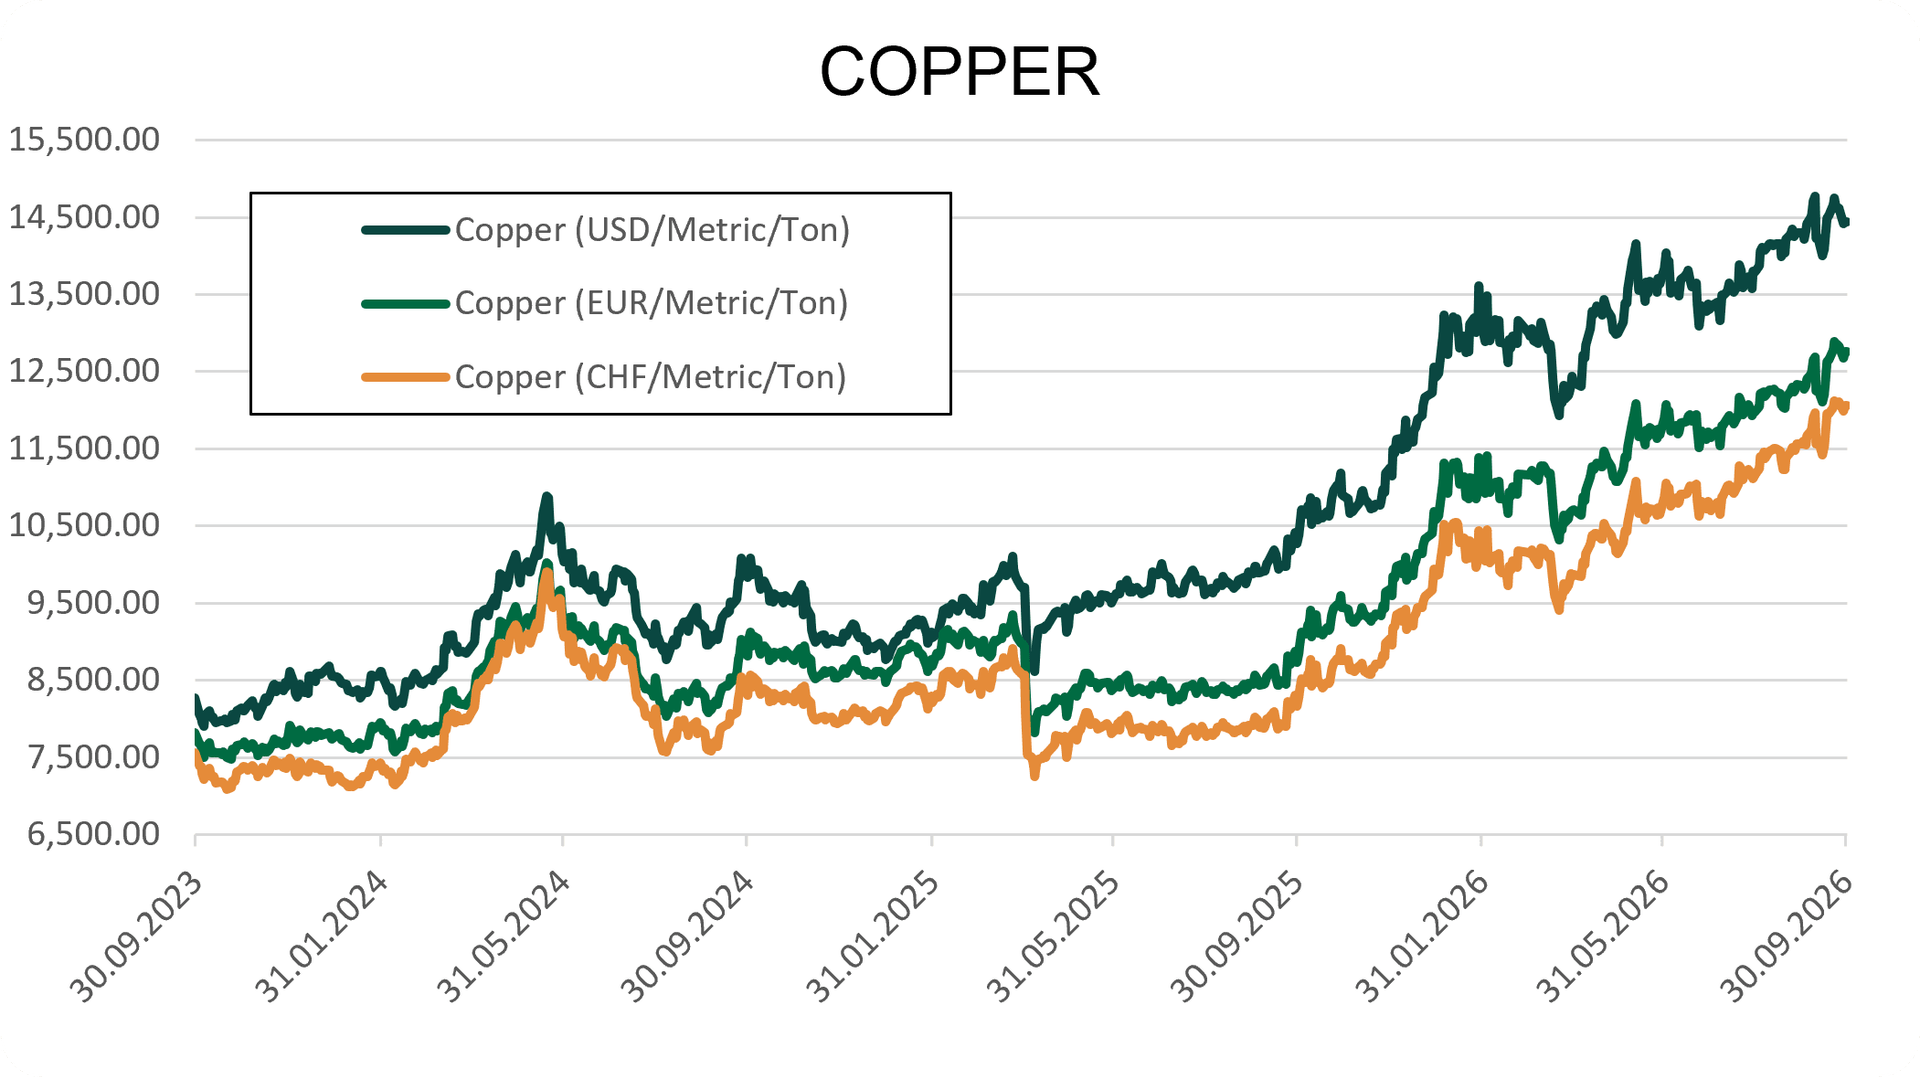
This market report was prepared on 09/30/2026.
OUR TEAM SUPPORTS YOU
Kerius Finance brings together a team of passionate experts dedicated to analyzing, managing, and optimizing financial risks. Our approach is based on transparency, rigor, and attentiveness, enabling us to fully understand your challenges and provide tailored solutions.