Market Letter - Novembre 2026
Currencies: The euro faces downward pressure from French sovereign debt concerns and rising energy costs.
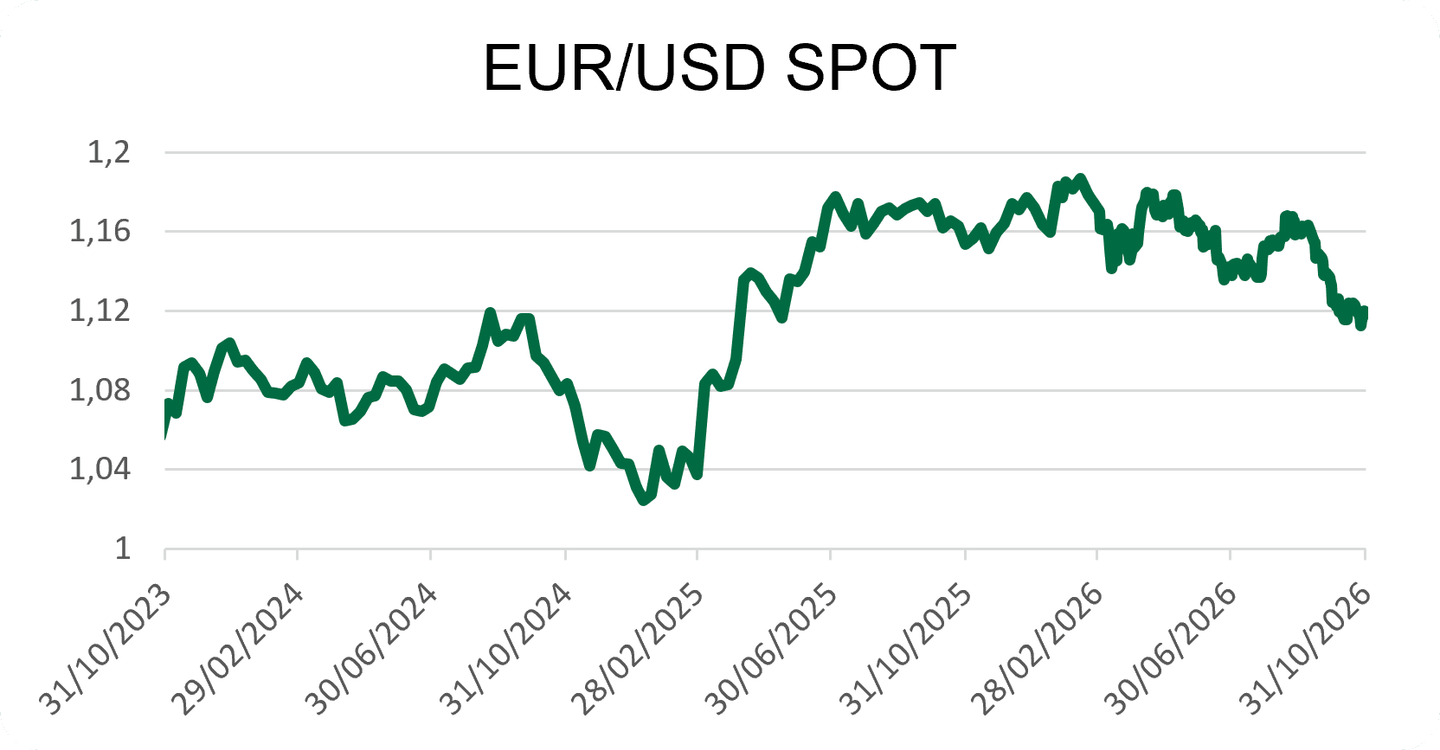
EURUSD: EURUSD is trading around 1.11, down 2.0% since the end of September. The US dollar remains supported by high US interest rates, while geopolitical tensions, energy pressures, and French fiscal concerns weigh on the euro.
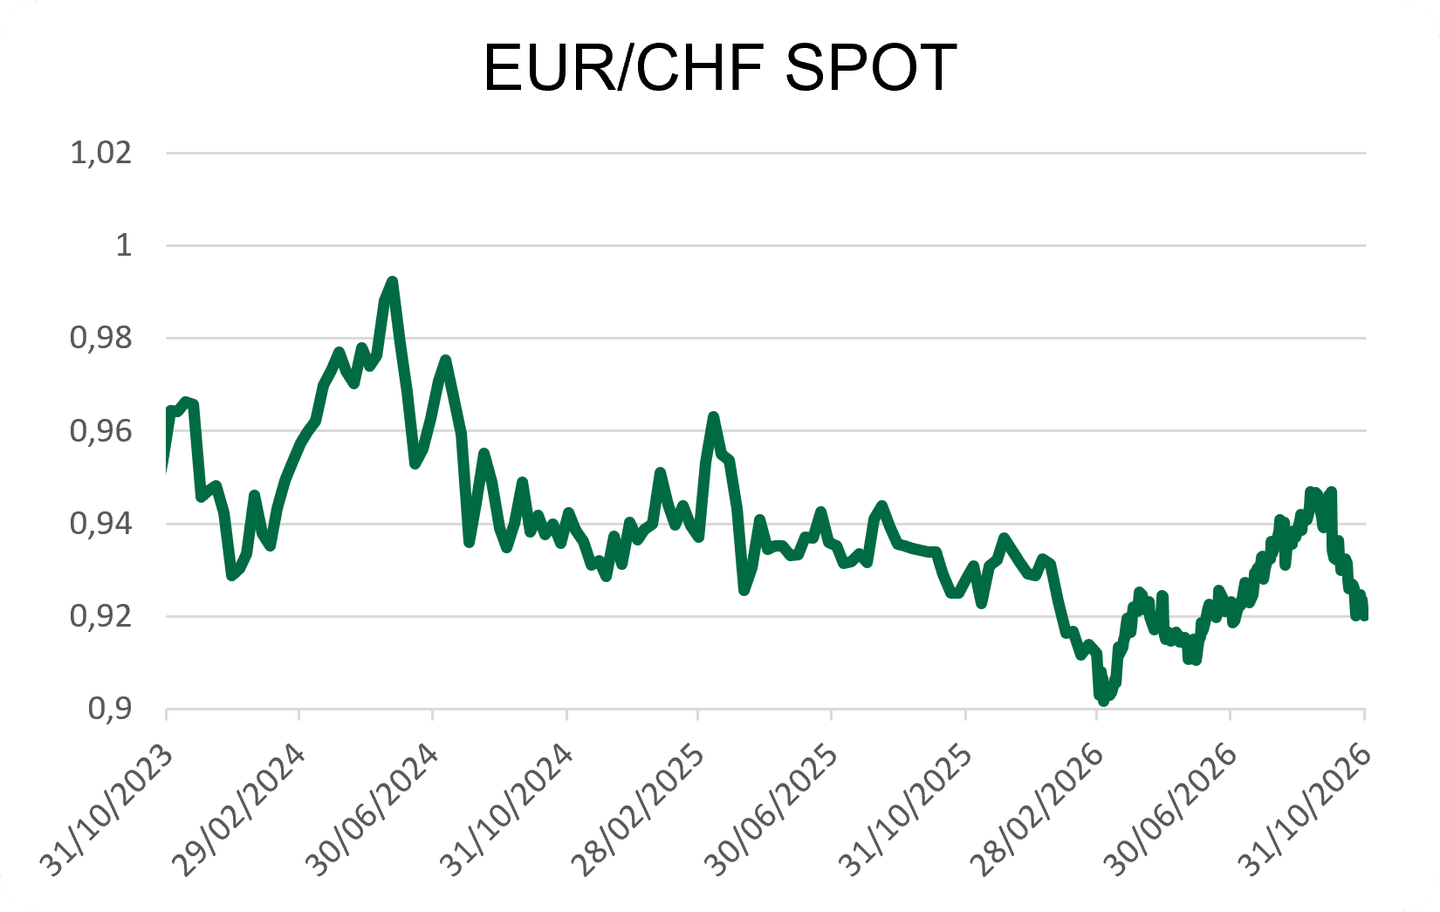
EURCHF: EURCHF is trading around 0.925, down 2.4%. The Swiss franc benefits from its safe-haven status despite the Swiss National Bank (SNB) maintaining its policy rate at 0%.
EURCNY: EURCNY is trading around 7.42, down 2.5%. The yuan benefits from the euro’s weakness, while China maintains its loan prime rates at 3.0% and 3.5%, with economic growth reaching 4.5% in the third quarter.
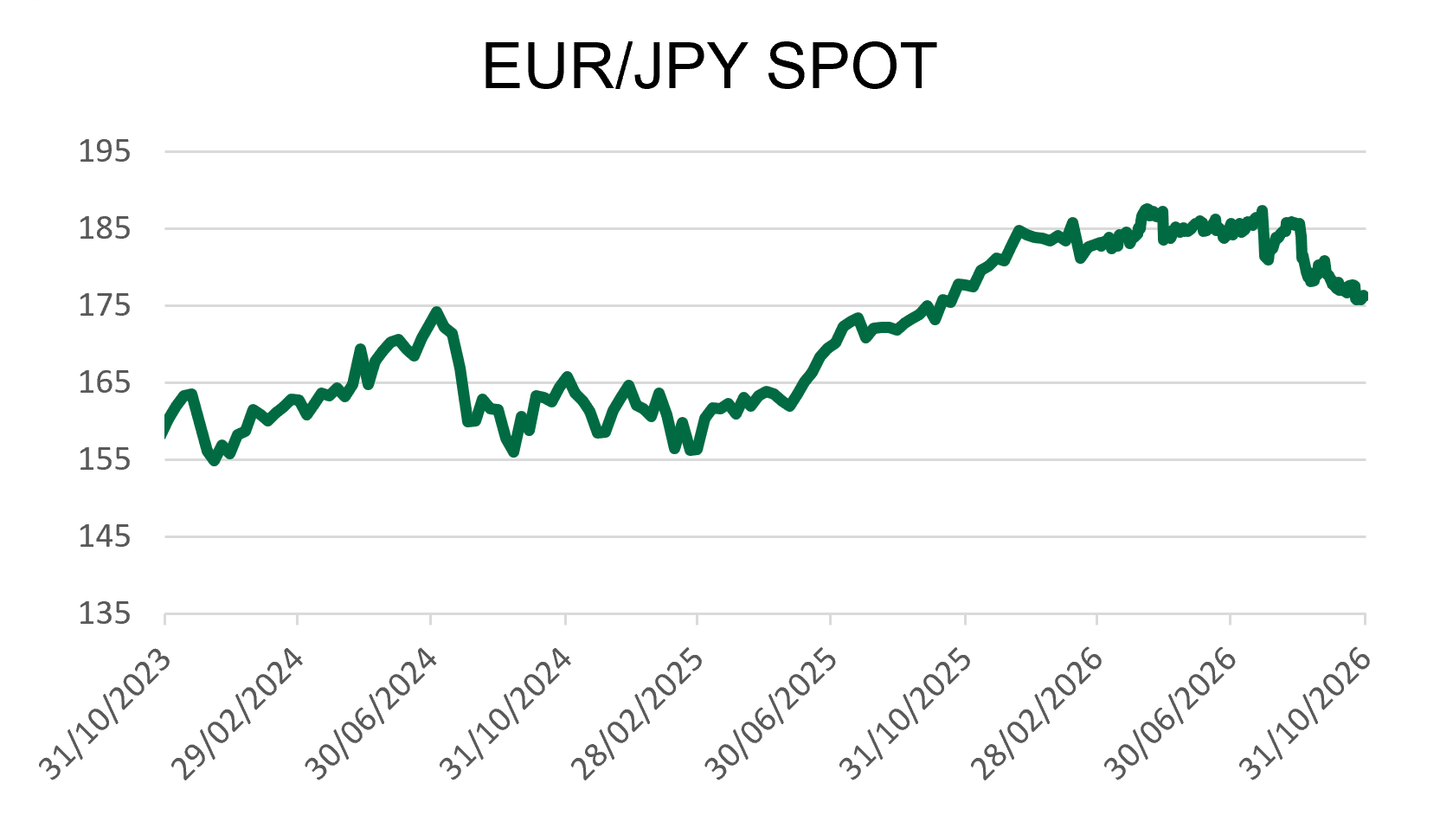
EURJPY: EURJPY is trading around 176, down 1.4%. The yen is strengthening against the euro, supported by expectations of further Japanese interest rate hikes, with the policy rate currently at 1.25%.
EURBRL: EURBRL is trading around 5.93, up 0.4%. Lula’s re-election on October 25 triggered significant volatility in the Brazilian real, as investors expressed concerns about the outlook for Brazil’s public finances.
EURZAR: EURZAR is trading around 18.53, down slightly by 0.4%. The South African rand remains supported by high interest rates at 7.25%, but is still vulnerable to geopolitical tensions and rising energy costs.
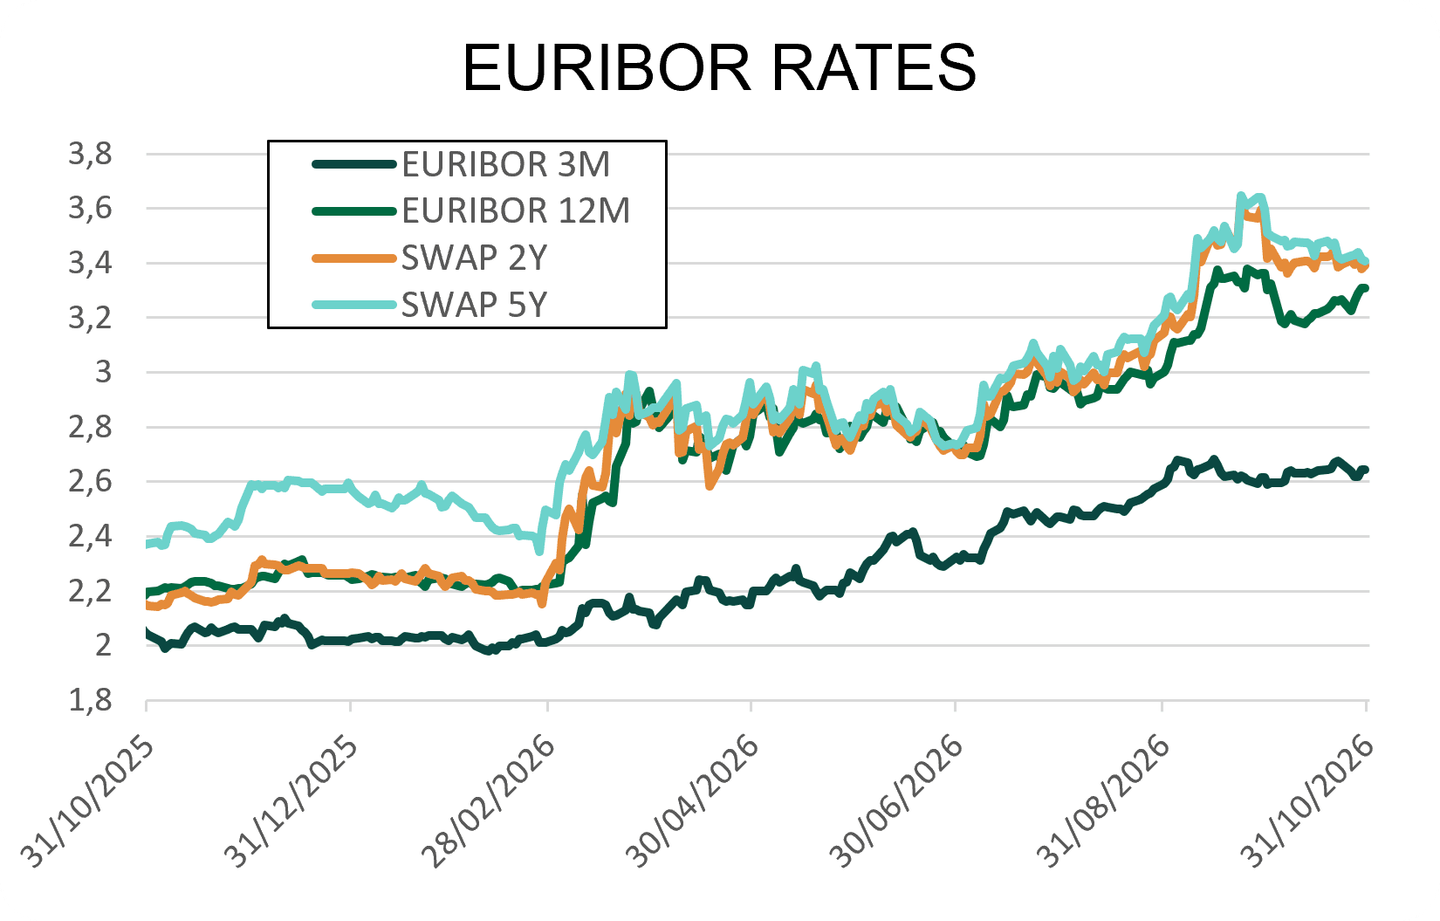
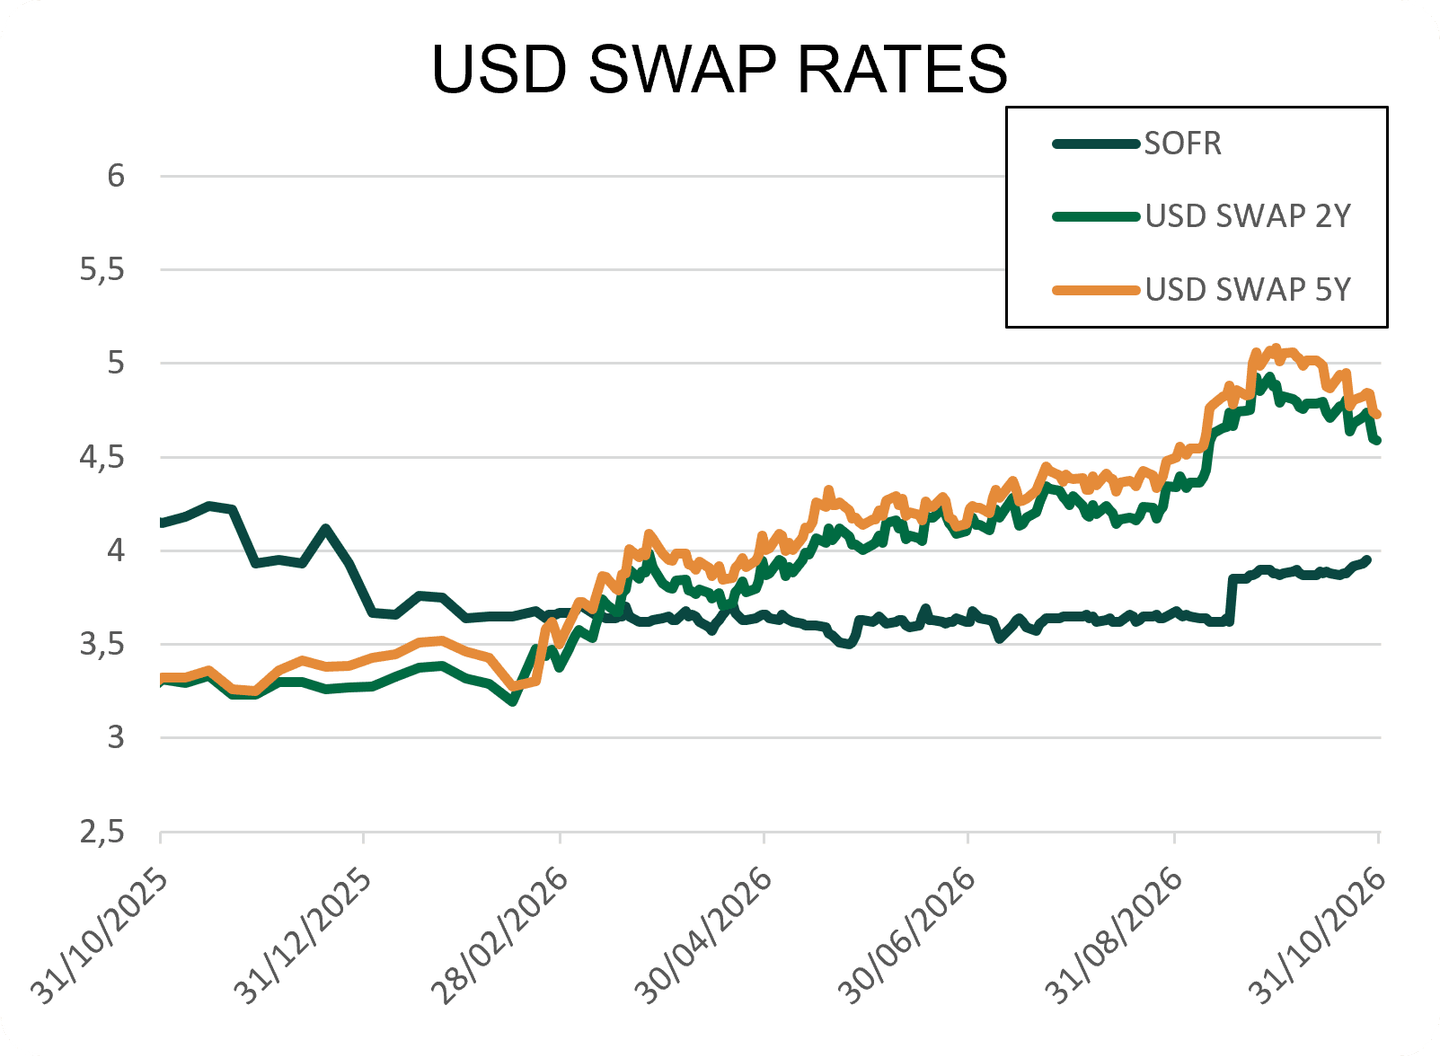
Interest Rates: Central banks remain cautious due to persistent inflationary pressures.
United States: The Federal Reserve kept its policy rate unchanged at 3.75%–4.00% on October 28, despite inflation reaching 3.7% in September. Another rate hike remains possible in December. The 10-year US Treasury yield is trading around 5.05%.
Euro Area: The European Central Bank (ECB) maintained its deposit rate at 2.50% following its October 29 decision, while inflation reached 3.8% in September. The composite PMI slowed to 51.9 in October, while energy pressures and French fiscal tensions weigh on the economic outlook.
United Kingdom: The Bank of England (BoE) maintained its policy rate at 3.75%. Inflation reached 3.5% in September, driven partly by higher fuel prices. The BoE remains cautious amid risks of persistent inflationary pressures.
Japan: On October 30, the Bank of Japan (BoJ) maintained its policy rate at 1.25%, in line with market expectations. Inflation reached 2.1% in September. The BoJ raised its inflation forecasts for 2027 and reaffirmed its intention to continue gradually increasing interest rates, leaving open the possibility of another hike as early as December.
China: The People's Bank of China (PBoC) maintained its loan prime rates at 3.0% for one year and 3.5% for five years. Economic growth reached 4.5% in the third quarter, supported by industrial activity despite persistent weakness in the property sector.
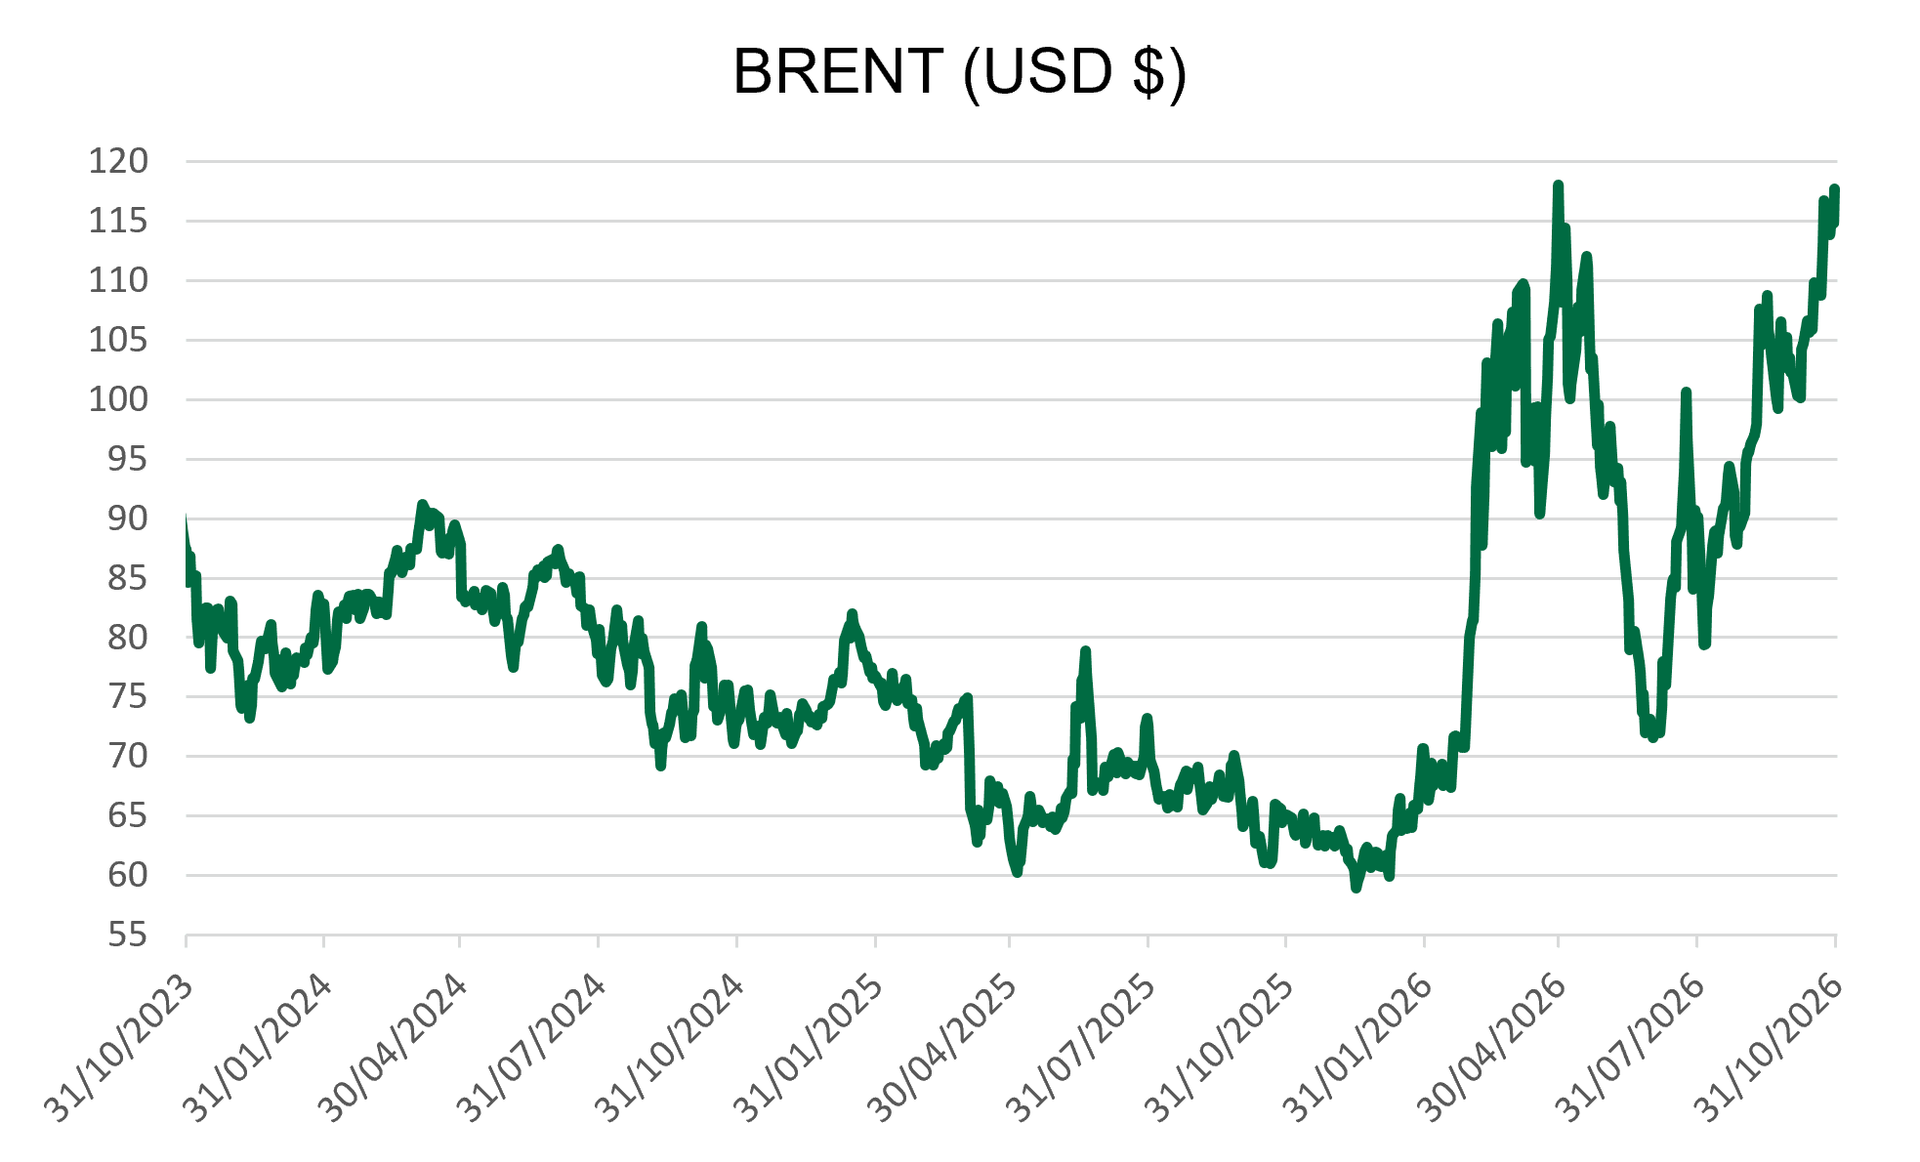
Commodities: Oil and gas prices reach new highs.
Oil: Brent crude is trading around $114 per barrel, up nearly 17% over the past month. Tensions in the Middle East, risks surrounding the Strait of Hormuz, and threats to Saudi oil infrastructure are supporting prices. The risk of regional escalation following the US midterm elections could further intensify upward pressure on oil prices.
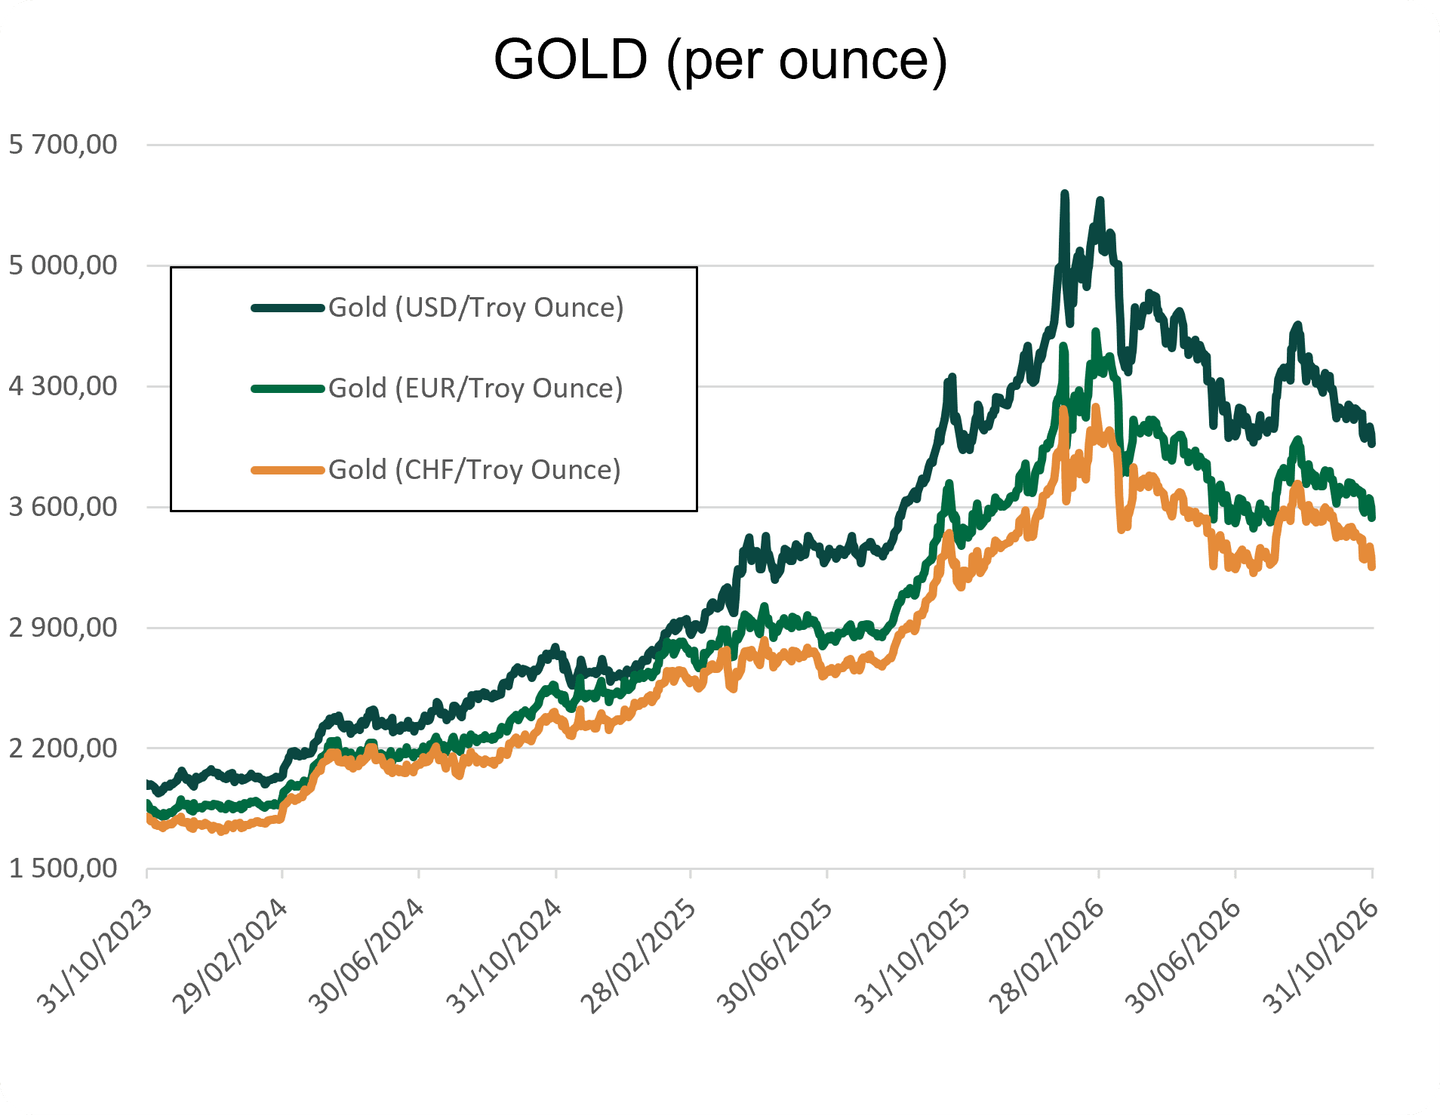
Gold: Gold is trading around $4,030 per ounce, down approximately 3% over the past month. A strong US dollar and elevated US bond yields are weighing on prices despite geopolitical tensions.
Sulfur: Sulfur is trading around CNY 5,560 per tonne, down 28% over the past month, but remains nearly 68% above its October 2025 level. Production costs for fertilizers and sulfuric acid remain under pressure.
Natural Gas / LNG: In the United States, natural gas is trading around $3.03/MMBtu, broadly stable over the past month thanks to abundant production. In Europe, the TTF benchmark has reached approximately €100/MWh, up 35%, with gas storage levels close to 75%, compared with a seasonal average of 86%. Disruptions to Qatari exports and tensions in the Strait of Hormuz are supporting prices. In Asia, the JKM LNG benchmark has reached $32.4/MMBtu, up 27%. The approaching winter increases the risk of higher energy costs for European industry.
GPUs / AI: Demand for computing capacity remains strong. At Lambda, renting an Nvidia B200 costs between $6.69 and $6.99 per GPU per hour, compared with approximately $3.99–$4.29 for an H100 SXM. Investment in artificial intelligence continues to support pricing for high-end GPUs.
Copper: Copper is trading around $6.63 per pound, up approximately 1% over the past month. Electrification and investment in data centers are supporting prices, despite fragile Chinese demand.
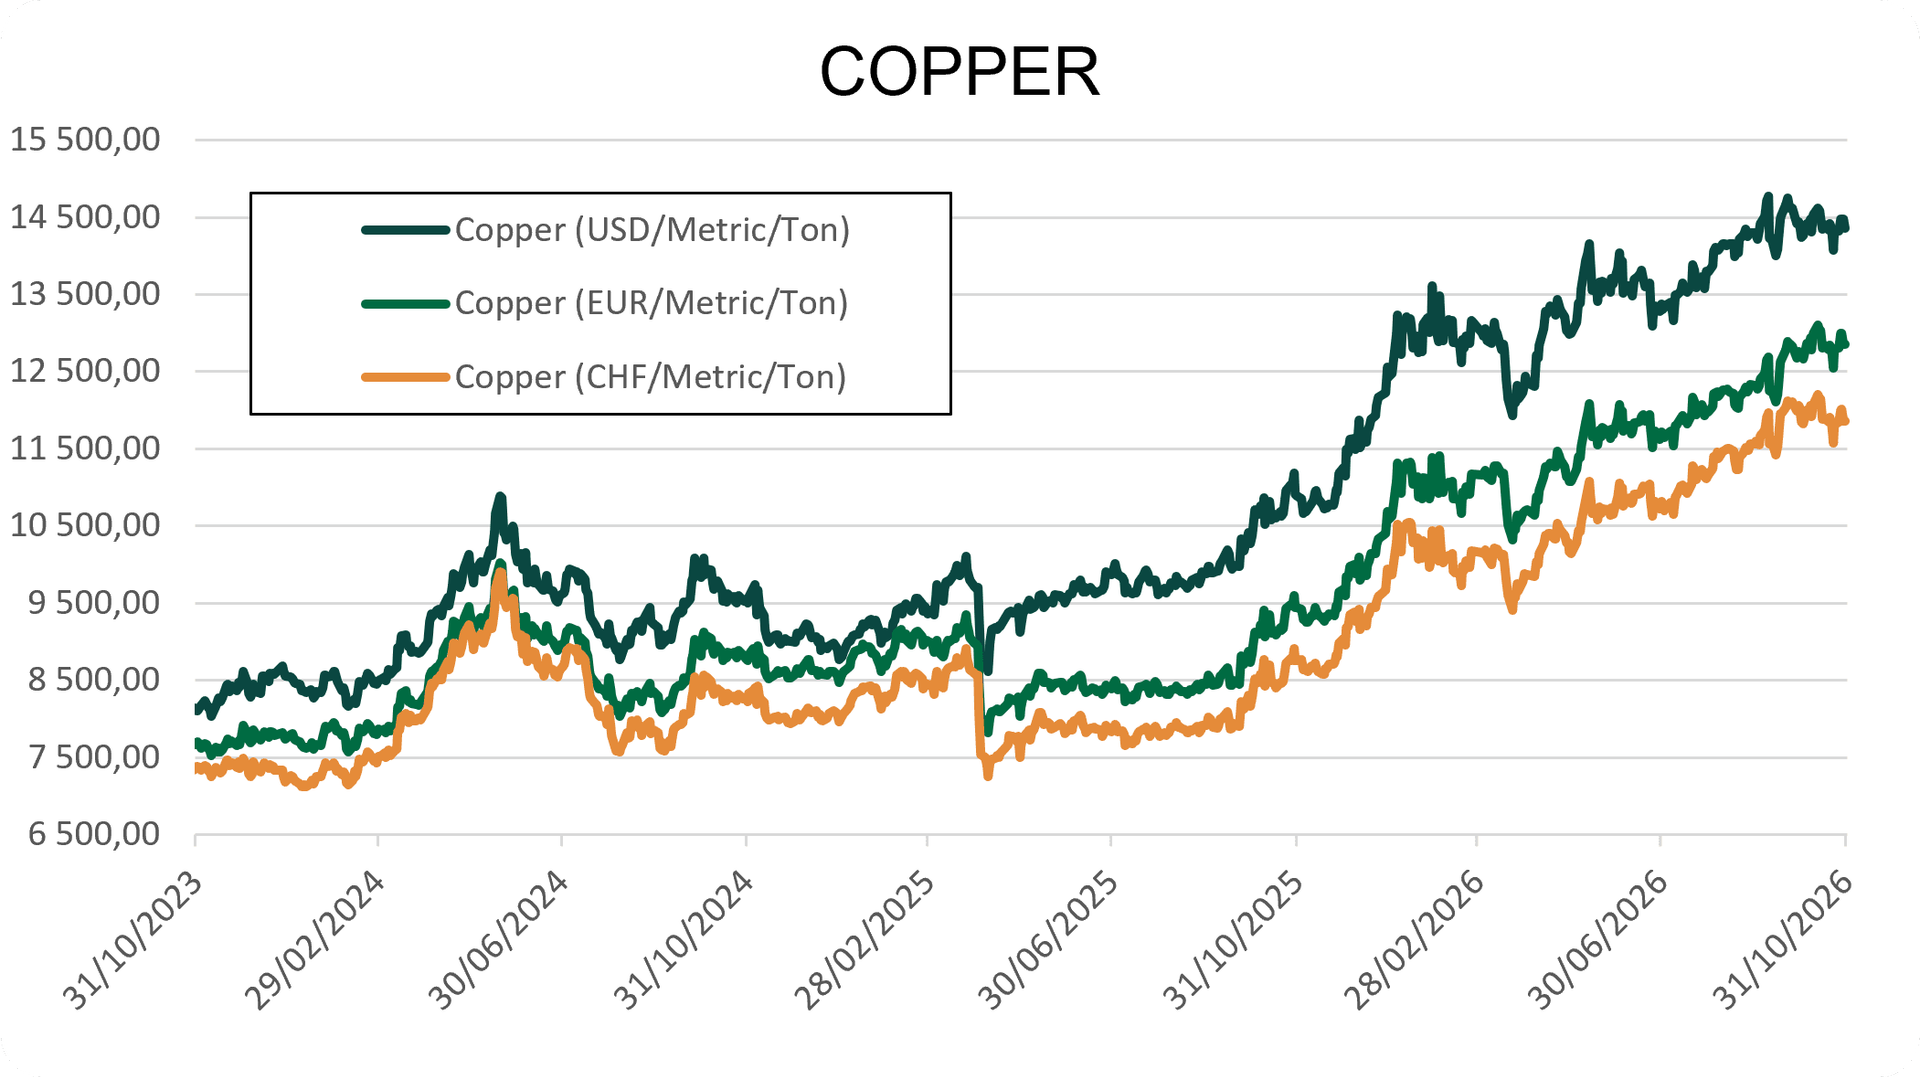
This market report was prepared on 10/30/2026.
OUR TEAM SUPPORTS YOU
Kerius Finance brings together a team of passionate experts dedicated to analyzing, managing, and optimizing financial risks. Our approach is based on transparency, rigor, and attentiveness, enabling us to fully understand your challenges and provide tailored solutions.